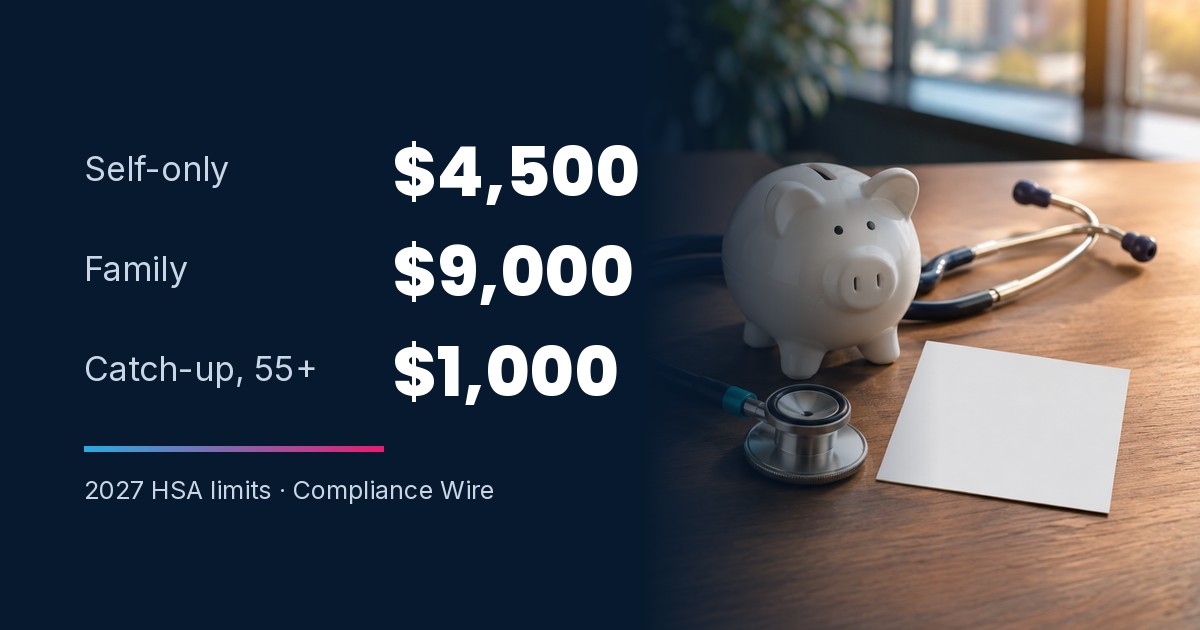
HSA: 2027 limits are $4,500 self-only and $9,000 family
The IRS raised the 2027 limits on health savings account contributions.
Status: Effective Jan 1, 2027
Jurisdiction: Federal · Topic: Health benefits
Source: IRS, May 29, 2026
What changed
The IRS raised the 2027 limits on health savings account contributions. The limit counts employer and employee contributions together, and money that goes in through a cafeteria plan comes out of pay before tax.
2027 vs. 2026
2027
2026
The math for family coverage at 55 or over
Compliance note
The limit counts employer and employee contributions together, so an employer contribution uses part of the employee’s room.
Who this affects
Employers that offer a high deductible health plan with an HSA, and the employees who contribute to an HSA through payroll.
Exceptions that matter:
- To qualify in 2027, a health plan needs a deductible of at least $1,750 for self-only coverage or $3,500 for family coverage, and an out-of-pocket maximum of no more than $8,700 or $17,400.
- The $1,000 catch-up at age 55 and over is set by law and does not rise with inflation.
What to do
Update the HSA limits in payroll before your first January pay date, and count any employer contribution toward each employee’s limit.
Employer checklist
Primary source: IRS, May 29, 2026. Part of Compliance Watch, Issue 05 (November 13, 2026). Last reviewed November 13, 2026.
Questions employers ask
When does this take effect?
Does an employer contribution count toward the limit?
Who can contribute to an HSA?
HSA limits, benefits and payroll
VertiSource HR places and administers employee benefits and runs payroll for its clients. Employees make their benefit choices in the same portal and phone app where they see their pay stubs.
Ask us about a federal rule All 3 updates in Issue 05
General information from VertiSource HR, not legal or tax advice. How a rule applies depends on your company and your state. Check with us or your attorney before acting.
Have a question on this?
Talk to the VertiSource HR specialist who handles compliance wire work every day. No script, no sales drip.
Get your free HR review