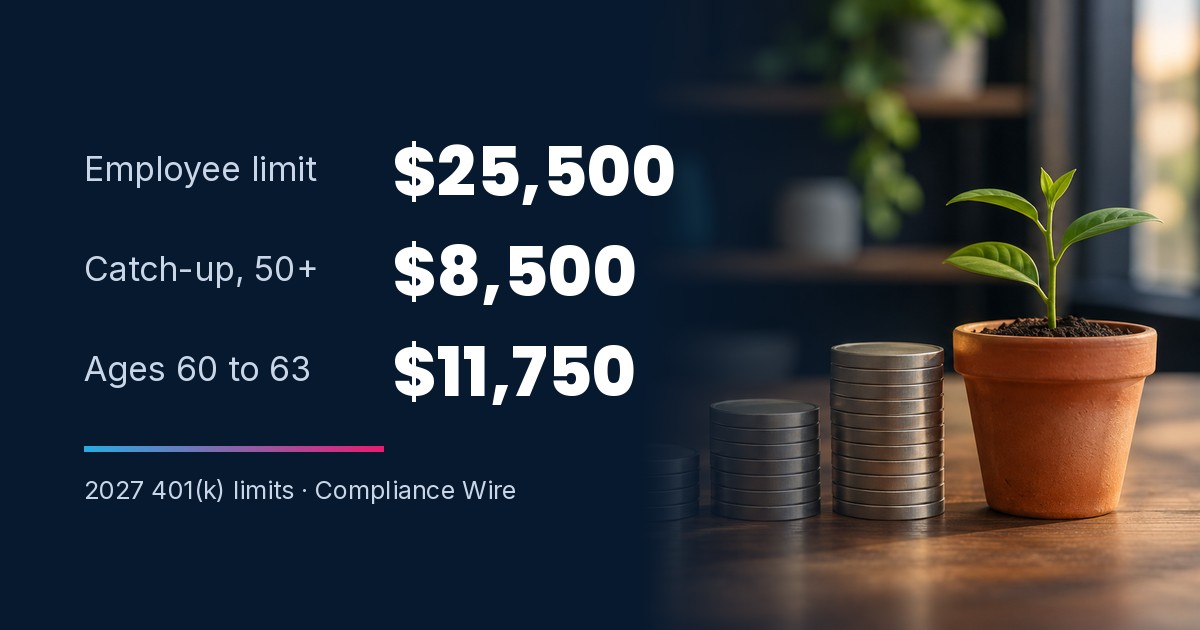
401(k): employee limit rises to $25,500 for 2027
The IRS raised the most an employee can put into a 401(k) from pay in 2027, pre-tax and Roth contributions combined, along with both catch-up limits.
Status: Effective Jan 1, 2027
Jurisdiction: Federal · Topic: Retirement plans
Source: IRS, November 12, 2026
What changed
The IRS raised the most an employee can put into a 401(k) from pay in 2027, pre-tax and Roth contributions combined, along with both catch-up limits. The same limits apply to 403(b) and most 457 plans.
2027 vs. 2026
2027
2026
The math for an employee 50 or over
Compliance note
An employee whose 2026 Social Security wages (W-2, Box 3) from the employer sponsoring the plan were more than $155,000 must make 2027 catch-up contributions as Roth.
Who this affects
Employers that sponsor a 401(k), 403(b) or governmental 457 plan, and the employees who contribute to it through payroll.
Exceptions that matter:
- The ages 60 to 63 catch-up takes the place of the age 50 and over catch-up, and applies only if the plan offers it.
- The total with employer money does not count catch-up contributions.
- A plan can set a lower limit than the IRS maximum.
What to do
Confirm payroll has the 2027 limits before your first January pay date, and tell employees who want to contribute more to change their election.
Employer checklist
Primary source: IRS, November 12, 2026. Part of Compliance Watch, Issue 05 (November 13, 2026). Last reviewed November 13, 2026.
Questions employers ask
When does this take effect?
Do pre-tax and Roth contributions share the limit?
Who can make catch-up contributions?
401(k) limits and your payroll
VertiSource HR runs payroll and payroll tax for its clients and provides 401(k) and retirement plans among its services. Each client has a direct line to their own payroll specialist, the same person year after year.
Ask us about a federal rule All 3 updates in Issue 05
General information from VertiSource HR, not legal or tax advice. How a rule applies depends on your company and your state. Check with us or your attorney before acting.
Have a question on this?
Talk to the VertiSource HR specialist who handles compliance wire work every day. No script, no sales drip.
Get your free HR review